A slower recent pace can coexist with a higher year-to-date total
Argentina’s national headline CPI rose 1.7% in August 2026 against the previous month, following July’s 2.1%, according to the supplied report. Its 12-month rate was 33.5%. A lower positive monthly rate means a slower increase in the aggregate measure, not a return to an earlier price level.
The report gives January–August inflation of 21.4% in 2026 and 19.5% in 2025, comparing eight months in each year. For recent pace, it supplies an average monthly change of 1.90% in June–August 2026, against 2.70% in March–May: three observations per group. Those averages are not accumulated three-month inflation.
Interpretation: the recent monthly pace has eased within this sample, but the increase accumulated over the current year remains above the same period of 2025. These statements describe different windows. Neither establishes the next month’s rate or explains the causes of the change.
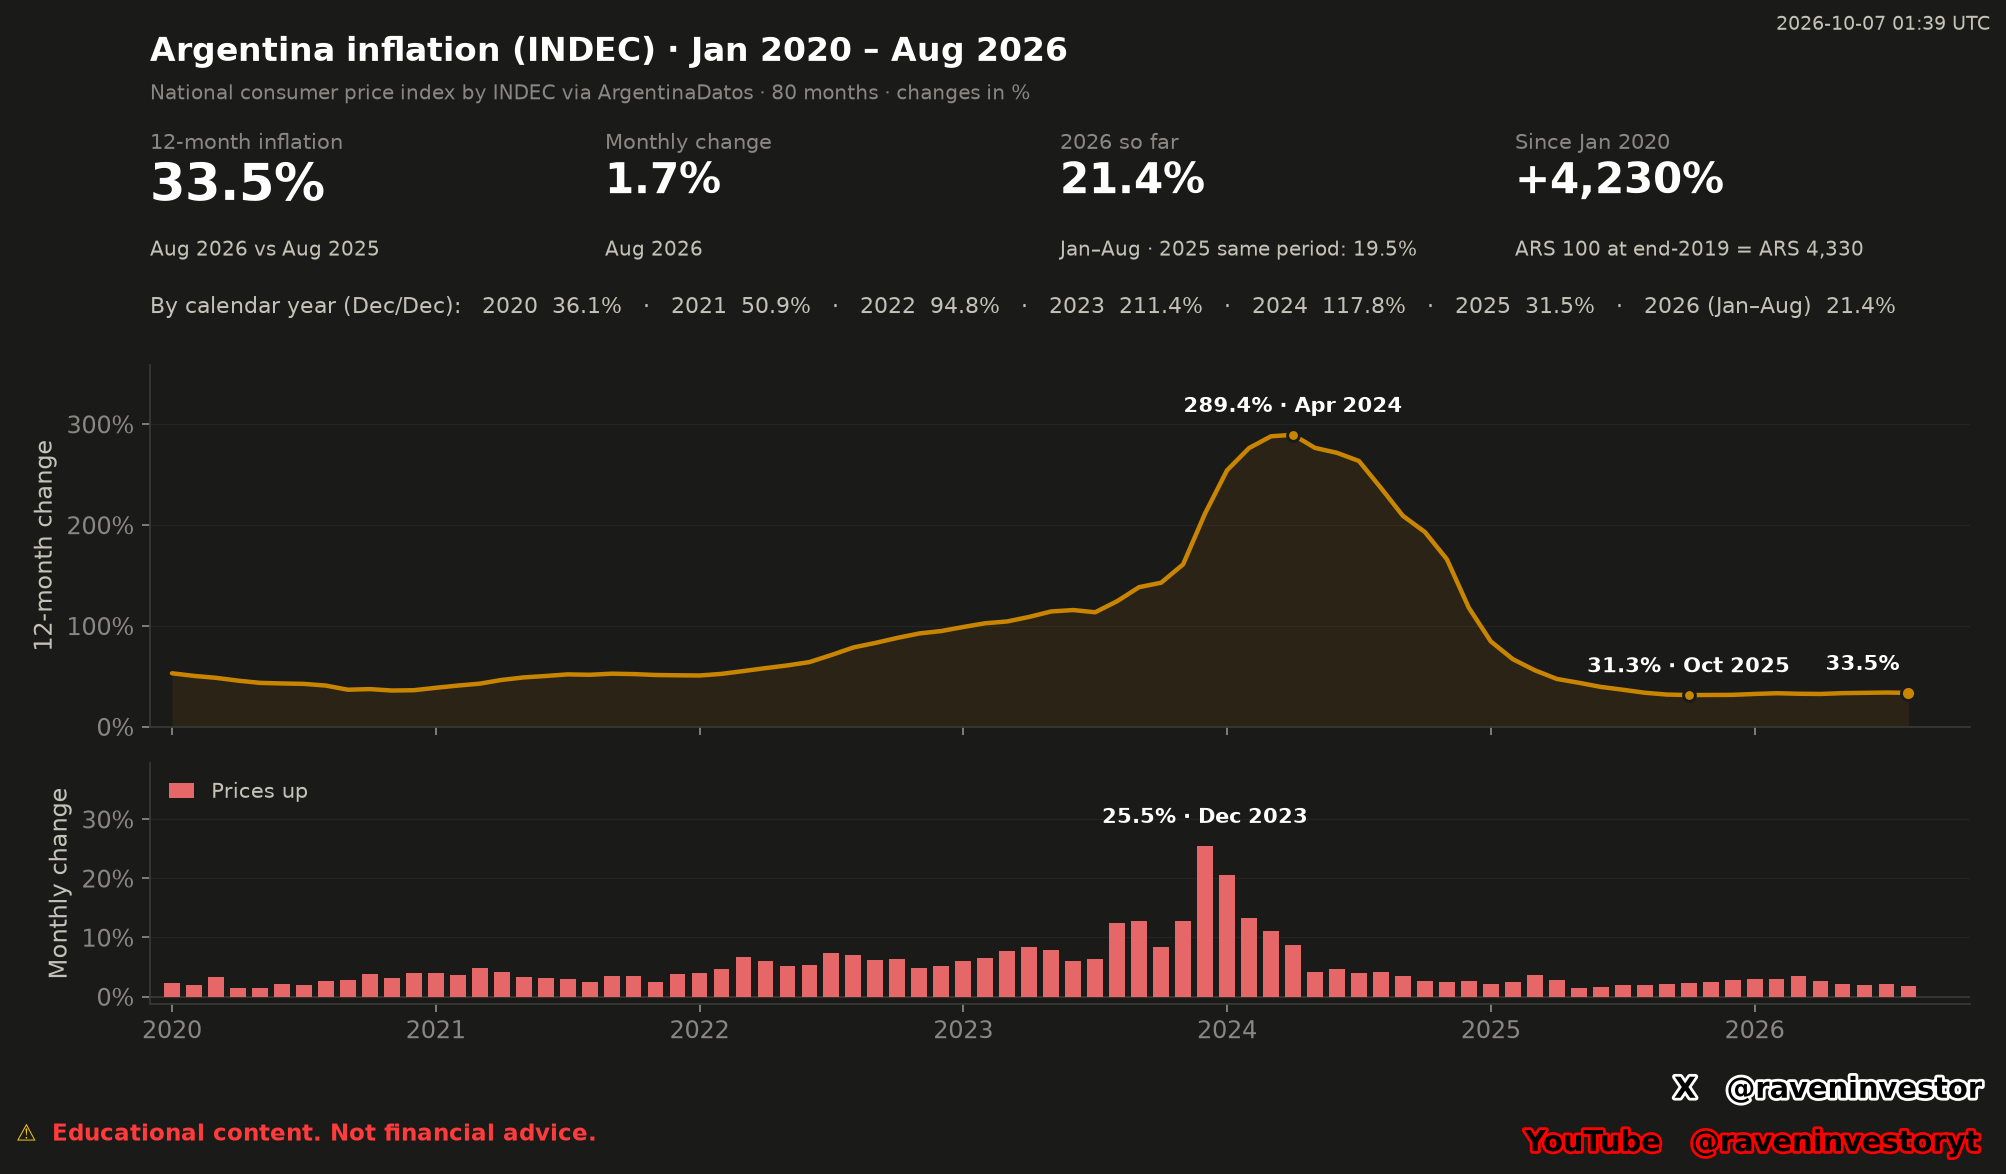
The chart shows rates of change, not the price level
The four summary cards distinguish August’s 12-month rate, August’s monthly change, January–August 2026 and the full period since January 2020. The calendar-year line compares December with the previous December for completed years. Its 2026 entry is explicitly partial, not a full-year result.
Across the 80-month sample, the gold line reaches its reported 12-month maximum of 289.4% in April 2024 and minimum of 31.3% in October 2025, before ending at 33.5%. A decline in this line indicates a lower rate relative to a year earlier; it does not, by itself, mean the aggregate price level fell.
The lower panel contains monthly changes for the same 80 months. All are positive. The highest is December 2023’s 25.5%, which is a different observation and horizon from the upper panel’s peak. The table contains a shared minimum of 1.5% in April 2020, May 2020 and May 2025; April 2020, named in the report’s summary, is not the only occurrence.
The panels have different vertical scales. Their heights should not be compared as if they measured the same period. The chart’s cumulative card rounds the reported ARS 4,329.96 illustration to ARS 4,330; the text below preserves the report’s precision.
The eight observations behind the latest 2026 readings
This extract contains January–August 2026: eight months within the full 80-month sample. Each row places the monthly rate beside the rate against the same month a year earlier. They are separate reported measures, not values to add together. September–December are absent from the snapshot, not zero.
| Month | Monthly change | 12-month change |
|---|---|---|
| 2026-01 | 2.9% | 32.4% |
| 2026-02 | 2.9% | 33.1% |
| 2026-03 | 3.4% | 32.6% |
| 2026-04 | 2.6% | 32.4% |
| 2026-05 | 2.1% | 33.2% |
| 2026-06 | 1.9% | 33.5% |
| 2026-07 | 2.1% | 33.8% |
| 2026-08 | 1.7% | 33.5% |
For a comparison of two observations within the full sample, August 2026’s 12-month rate of 33.5% is close to August 2025’s 33.6%. The report states a reduction of 0.1 percentage points. That is a change in the inflation rate, not a 0.1% decline in the price level.
Historical comparison: six completed calendar years
The table compares the six completed years, 2020–2025, in the 80-month study. Each value is the published December-to-December rate. The highest is 2023, at 211.4%; the lowest is 2025, at 31.5%. The partial 2026 result of 21.4% is excluded from this full-year ranking.
| Year | Reported annual inflation |
|---|---|
| 2020 | 36.1% |
| 2021 | 50.9% |
| 2022 | 94.8% |
| 2023 | 211.4% |
| 2024 | 117.8% |
| 2025 | 31.5% |
Interpretation: the lower rate in the latest completed year describes less inflation than at the annual peak, not a reversal of the accumulated price increase. These comparisons are descriptive. Historical similarity does not guarantee the same future outcome.
What the ARS 100 illustration does—and does not—say
For the 80-month January 2020–August 2026 window, the report supplies cumulative inflation of 4,230.0%. It illustrates this as ARS 100 at end-2019 corresponding to ARS 4,329.96 in August 2026 under the chained series. The starting point is end-2019, so January 2020’s change is included.
This is a reference-price comparison. It is not an investment return, a personal salary requirement or proof that every household’s expenses rose by exactly that amount. Nor is the cumulative inflation percentage itself a reported percentage loss of purchasing power. The study does not supply that separate calculation.
The report warns that chaining changes published to one decimal can differ by a few tenths from agency totals. The illustration and cumulative rate are therefore presented as supplied, without recalculating them or labeling them independently verified official index-level results.
Methodology, source coverage and limits
The report and image were generated October 7, 2026 at 01:39 UTC. Their latest reference month is August 2026. The declared source is INDEC’s national headline CPI through api.argentinadatos.com. The general multi-country pipeline also uses CEPALSTAT indicator 365, but its Argentina series covers Greater Buenos Aires and is not the national series used here.
Monthly and 12-month rates are the published changes against the preceding month and the same month a year earlier. Completed-year inflation uses December’s official 12-month rate. Current-year accumulation chains monthly changes; the long-window total chains completed-year December rates with the current-year accumulation. The input contains published variations, not index levels. No new financial calculations were performed for this article.
According to the report, our own system retains raw source responses with SHA-256 fingerprints. The broader database contains 720 monthly records for nine countries; the sample here is Argentina’s 80 months. It records no agency corrections at this snapshot, which does not rule out later revisions.
The evidence measures inflation in pesos, not changes in dollar-denominated prices, and does not cover years before 2020. It contains no spending-category contributions or causal analysis, so it cannot identify which factors drove the movements. The raw agency responses were not independently reprocessed for this article.
Sources and data fingerprint
Sources: RavenInvestor report and original chart, October 7, 2026, 01:39 UTC; declared underlying series: INDEC national headline CPI via ArgentinaDatos, January 2020–August 2026. CEPALSTAT’s Greater Buenos Aires series is not substituted for the national data. Declared data channel: ArgentinaDatos.
Data fingerprint declared by the report: 324ba0e3f549d6d1. Identifies the supplied version; it is not an independent audit of the underlying source data.